Nov 19, 2026
These 7 Retirement Planning Mistakes Could Leave You Financially Unprepared Later
- Sarah Nelson

How to Choose a Home Equity Line of Credit for Your Financial Needs
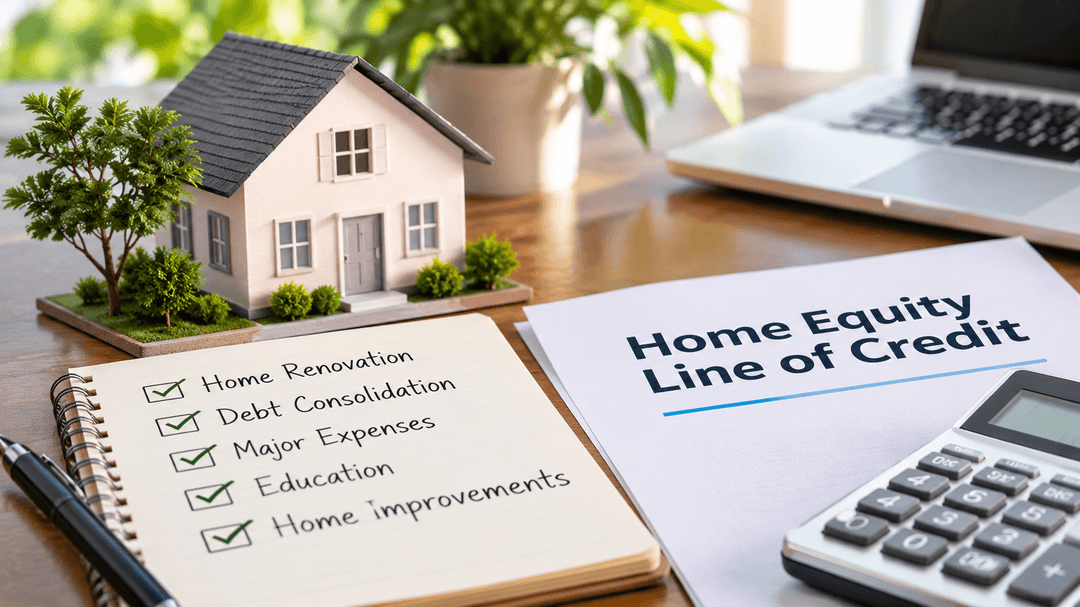
A Home Equity Line of Credit (HELOC) may provide homeowners with a flexible way to access funds using the equity they have built in their property.
Unlike traditional loans that distribute a fixed amount upfront, a HELOC generally allows borrowers to withdraw money as needed, up to an approved credit limit.
Homeowners often explore this financing option when planning renovations, covering significant expenses, or consolidating existing debt. However, understanding how HELOCs work, their potential costs, and their repayment requirements can help borrowers make informed financial decisions.
Before applying, it helps to compare borrowing terms, interest rates, fees, and eligibility requirements to determine if this type of financing fits your financial situation.
A Home Equity Line of Credit is a revolving credit arrangement secured by a residential property. The amount available to borrow generally depends on the homeowner’s equity, creditworthiness, income, existing debt, and the lender’s requirements.
Home equity represents the difference between a property’s current market value and the outstanding mortgage balance and other liens.
For example, if a home has an estimated value of $350,000 and the remaining mortgage balance is $200,000, the homeowner has approximately $150,000 in equity.
However, this does not mean the homeowner can borrow the entire $150,000. Lenders typically establish borrowing limits based on their loan-to-value requirements and other financial considerations.
A HELOC generally operates through two periods:
1. Draw Period
During the draw period, borrowers can access funds up to their approved credit limit. Depending on the agreement, they may be able to borrow, repay, and borrow again.
Some HELOCs permit interest-only payments during this period, although payment requirements vary.
2. Repayment Period
Once the draw period ends, borrowers generally can no longer withdraw funds and must repay the outstanding balance according to the agreement.
Monthly payments may increase significantly when principal repayment begins, particularly if the borrower previously made interest-only payments.
Understanding these phases can help homeowners prepare for changes in their monthly financial obligations.
A HELOC may be suitable for homeowners who need access to financing over an extended period rather than receiving one large payment.
One potential advantage is the ability to withdraw funds when necessary. This flexibility may be helpful for projects with expenses that occur at different times.
For example, homeowners completing renovations may need financing for materials, contractors, and unexpected repairs throughout the project.
With many HELOC arrangements, interest is charged on the outstanding amount borrowed rather than the entire approved credit limit.
This feature may help borrowers manage interest expenses when they do not need all available funds immediately.
However, annual fees, inactivity charges, and other expenses may still apply depending on the agreement.
Because a HELOC is secured by property, its interest rate may be lower than rates associated with certain unsecured borrowing options.
However, the actual rate depends on factors such as credit history, market conditions, and the lender’s pricing structure.
HELOC funds may be used for several purposes, depending on the agreement, including home improvements, education expenses, major repairs, and debt consolidation.
Borrowers should evaluate the financial impact of each expense before using their home as collateral.
When comparing financing options, homeowners frequently examine a home equity loan alongside a HELOC.
Although both generally use property equity as collateral, they have different borrowing and repayment structures.
| Feature | Home Equity Line of Credit | Home Equity Loan |
|---|---|---|
| Funding | Withdraw funds as needed | Receive a lump sum |
| Interest rate | Usually variable | Often fixed |
| Payments | May change over time | Often predictable |
| Borrowing access | Revolving during draw period | Generally one-time funding |
| Suitable expenses | Ongoing or uncertain costs | Known, fixed expenses |
| Main consideration | Variable payments and rate changes | Interest on the full loan balance |
A HELOC may be practical for projects with changing expenses, while a home equity loan may suit borrowers who already know exactly how much financing they need.
Neither option is automatically better. The appropriate choice depends on repayment preferences, financial stability, and borrowing goals.
Understanding HELOC interest rates is important because many agreements use variable rates that can change over time.
These rates are commonly tied to a benchmark, such as the prime rate, plus or minus a lender-determined margin.
When the benchmark increases, the interest charged on an outstanding balance may increase. When it decreases, borrowing costs may decline, subject to the agreement’s terms.
The following table illustrates approximate monthly interest charges on a $40,000 outstanding balance at different annual interest rates.
| Annual Interest Rate | Approximate Monthly Interest |
|---|---|
| 6% | $200 |
| 7% | $233 |
| 8% | $267 |
| 9% | $300 |
These examples use a simplified annual-rate calculation divided by 12. Actual charges may depend on daily balances, billing cycles, and other agreement terms. Principal payments and fees are excluded.
A relatively small rate increase may affect monthly borrowing costs, particularly when the outstanding balance is substantial.
Before applying, homeowners should review the rate adjustment terms, any introductory pricing, applicable caps, and the repayment schedule.
Meeting HELOC requirements generally involves demonstrating sufficient property equity and the financial ability to repay borrowed funds.
Although qualification standards vary, lenders commonly review the following factors.
Homeowners generally need enough equity to support the requested credit limit.
Lenders may calculate a combined loan-to-value ratio, which accounts for the existing mortgage and the proposed HELOC.
For example, a property valued at $400,000 with an outstanding mortgage of $240,000 would have a current loan-to-value ratio of 60% before additional borrowing.
The amount available through a HELOC would depend on the lender’s permitted combined loan-to-value ratio and other eligibility criteria.
A borrower’s credit history may influence approval decisions, borrowing limits, and interest rates.
A stronger credit profile may improve access to favorable terms, although approval is never guaranteed.
Lenders generally assess income stability and available financial resources to determine repayment capacity.
Self-employed applicants may need to provide additional financial documentation.
The debt-to-income ratio compares monthly debt obligations with gross monthly income.
A lower ratio may indicate greater capacity to manage additional borrowing, although each lender establishes its own standards.
Depending on the application, borrowers may need to provide mortgage statements, proof of homeowners insurance, property information, and income records.
An appraisal or another property valuation method may also be required.
A home equity calculator may help homeowners estimate how much equity they have and the potential amount they could borrow.
The basic formula is:
Home Equity = Estimated Property Value − Outstanding Mortgage Debt and Other Property Liens
For example:
| Calculation Item | Amount |
|---|---|
| Estimated property value | $450,000 |
| Outstanding mortgage | $275,000 |
| Estimated home equity | $175,000 |
| Current loan-to-value ratio | 61.1% |
If a lender permits a maximum combined loan-to-value ratio of 80%, the illustrative calculation would be:
$450,000 × 80% = $360,000
$360,000 − $275,000 = $85,000
In this example, the homeowner might qualify for a credit limit of up to $85,000 based on the property value and assumed borrowing cap alone.
The final approved amount may be lower because of credit qualifications, existing liens, income, and lender policies.
A HELOC may be suitable for certain expenses, particularly when the total amount or timing of costs is uncertain.
Common uses include:
Homeowners should avoid assuming that accessing available equity automatically improves their financial position.
Borrowing against a home creates an additional financial obligation and may reduce the equity available for future needs.
Before signing an agreement, borrowers should understand the full HELOC closing costs and ongoing expenses.
Depending on the lender and agreement, possible charges include application fees, appraisal expenses, annual fees, early termination charges, and other account-related costs.
Some lenders may waive certain upfront charges under specific conditions.
Variable interest rates: Monthly borrowing costs may increase when market rates rise.
Payment changes: Payments may become substantially higher after the draw period ends.
Property foreclosure risk: Because the home serves as collateral, failure to meet repayment obligations could result in foreclosure.
Reduced home equity: Borrowing against property equity decreases the homeowner’s remaining equity until the debt is repaid.
Credit line restrictions: Under certain circumstances, lenders may freeze or reduce an available credit line, subject to applicable law and contract terms.
Potential property value changes: Declining home values may affect the owner’s equity position and future borrowing flexibility.
These considerations make it important to evaluate repayment capacity before committing to a HELOC.
Homeowners researching HELOC lenders should compare the full borrowing arrangement rather than focusing exclusively on the advertised interest rate.
The following factors can help identify meaningful differences between financing options.
| Comparison Factor | What to Review |
|---|---|
| Interest rate | Introductory rate, variable-rate formula, and adjustment caps |
| Credit limit | Minimum and maximum borrowing amounts |
| Draw period | Length of time funds remain accessible |
| Repayment period | Required payments and repayment duration |
| Fees | Upfront, annual, inactivity, and termination charges |
| Payment structure | Interest-only or principal-and-interest requirements |
| Rate conversion | Availability and terms of fixed-rate features |
| Early repayment | Applicable restrictions or charges |
| Customer support | Access to account information and repayment assistance |
Clear answers can help borrowers identify costs and restrictions that may not be immediately obvious in promotional materials.
A HELOC may be appropriate for homeowners with sufficient equity, reliable income, and a clear repayment plan. However, its suitability depends on borrowing costs, financial goals, and the risks associated with using property as collateral.
Yes. Homeowners may qualify for a HELOC while continuing to pay an existing mortgage. Lenders generally evaluate the combined debt secured by the property when determining eligibility.
A formal application may involve a hard credit inquiry, which can temporarily affect a credit score. Opening and managing the account may also influence credit history and other scoring factors.
Many HELOC agreements permit funds to be used for a broad range of expenses. However, restrictions may apply, and borrowers should confirm permitted uses before withdrawing funds.
In the United States, interest deductibility depends on current tax law and how the borrowed funds are used.
Under rules applicable to qualifying periods, interest may be deductible when the funds are used to buy, build, or substantially improve the qualifying home securing the loan, subject to applicable limits and requirements.
Tax treatment can change, so homeowners should review current IRS guidance or consult a qualified tax professional.
An outstanding HELOC generally must be repaid when the property is sold. The balance is commonly settled from sale proceeds as part of the closing process.
Many HELOC agreements permit early repayment. However, some may include early closure charges or conditions involving previously waived fees. Reviewing the agreement can help borrowers understand any additional costs.
A Home Equity Line of Credit may provide flexible access to funds for homeowners who have sufficient equity and can manage the repayment requirements.
However, variable interest rates, changing monthly payments, account fees, and the risk of losing the property deserve careful attention.
Comparing financing options, reviewing the complete agreement, and estimating payments under different interest rate scenarios may help homeowners determine if a HELOC supports their financial plans.
The decision should reflect realistic borrowing needs and the ability to repay the outstanding balance without placing unnecessary pressure on household finances.