How Online Business Checking Account Features May Help Organize Company Finances
How Online Business Checking Account Features May Help Organize Company Finances
Managing company finances may become easier when business income and expenses have a dedicated place. An Online Business Checking Account may help business owners handle payments, deposits, transfers, and routine financial activity through digital banking platforms. Unlike accounts that rely heavily on branch visits, online business accounts typically allow account holders to complete many banking tasks through a website or mobile app.
Available functions, fees, transaction limits, eligibility requirements, and deposit services can vary by financial institution. Before selecting an account, businesses may benefit from reviewing how they receive payments, pay expenses, maintain cash reserves, and handle daily transactions. Understanding these needs can help narrow down account types that fit normal business activity.
What Is an Online Business Checking Account?
An Online Business Checking Account is a checking account designed for business transactions that can generally be managed through digital banking services.
Depending on the financial institution, account holders may be able to:
- View balances and transaction history
- Send or receive electronic payments
- Transfer funds between accounts
- Deposit eligible checks through a mobile app
- Pay bills electronically
- Manage debit cards
- Download statements
- Set account alerts
- Connect eligible accounting software
Account capabilities can differ. Some institutions operate entirely online, while others combine digital banking with access to physical branches.
A business bank account may also help keep company transactions separate from personal spending, which can make financial recordkeeping easier.
How Does Digital Business Banking Work?
Digital business banking allows businesses to access banking services through online portals or mobile applications. After an account is opened, an authorized user may log in to review balances, send payments, transfer funds, or manage account settings. Certain institutions may include additional business features, such as user permissions, transaction alerts, electronic bill payment, or accounting integrations.
The exact tools available depend on the account provider and account type. Businesses that handle most payments electronically may find digital account access practical. Companies that frequently deposit physical cash may need to check how cash deposits are handled before selecting an online account.
Online Business Checking Account Features to Review
Business checking accounts can differ significantly. Looking at several account details may help businesses identify a suitable option.
| Account Feature | What to Review | Why It May Matter |
|---|---|---|
| Monthly maintenance fee | Fee amount and possible requirements | May affect recurring banking costs |
| Opening deposit | Minimum amount needed to open an account | May affect initial account setup |
| Transaction limits | Number or type of included transactions | May matter for businesses with frequent activity |
| Cash deposits | Availability, limits, and possible charges | Important for businesses accepting cash |
| ATM access | Network availability and possible charges | May affect access to physical cash |
| Electronic transfers | Transfer availability, timing, and limits | Useful for paying vendors or moving funds |
| Mobile deposits | Eligibility and deposit limits | May reduce the need to deposit checks in person |
| Account integrations | Compatible bookkeeping or payment services | May simplify financial administration |
| Customer service | Support channels and operating hours | May matter when account assistance is needed |
Businesses should review the institution’s current account disclosures and fee schedule because terms may change.
What Fees May Apply to Business Checking Accounts?
Business checking fees vary by financial institution and account type.
Possible charges may include:
- Monthly maintenance fees
- ATM fees
- Wire transfer fees
- Cash deposit charges
- Overdraft-related charges
- Stop-payment fees
- Returned payment fees
- Excess transaction charges
- Paper statement fees
An account advertised without a monthly maintenance fee could still have charges for certain transactions or services. Businesses may want to review the complete fee schedule before opening an account.
Account terms may also include conditions that affect how certain charges are assessed.
Can an Online Business Checking Account Help With Cash Flow Management?
An Online Business Checking Account may support organized business cash flow by giving owners a central account for receiving revenue and paying operating expenses. Digital account access may make it easier to review recent activity, monitor balances, and identify upcoming payments.
Businesses might use checking account records to track items such as:
- Customer payments
- Vendor invoices
- Payroll-related transactions
- Software subscriptions
- Utility bills
- Inventory purchases
- Tax-related payments
- Business insurance expenses
Bank account activity does not replace formal bookkeeping. However, organized transaction records may support accounting and reconciliation processes.
Online Business Checking Account vs. Traditional Business Checking
Both account types can support routine business transactions, though access methods may differ.
| Online Business Checking | Traditional Business Checking |
|---|---|
| Primarily managed digitally | Often combines branch and digital access |
| May have limited physical branch access | Physical branches may be available |
| Digital tools may play a larger role | Digital tools may accompany in-person services |
| Cash deposit options can vary | Branch cash deposits may be available |
| Customer service may be digital or phone-based | In-person assistance may be available |
Neither account type automatically fits every company.
A business that receives mostly electronic payments may prioritize digital access. A company handling frequent cash transactions may place greater emphasis on physical deposit locations.
Who Might Use a Small Business Checking Account?
A small business checking account may be used by different types of businesses, including:
- Sole proprietors
- Limited liability companies
- Partnerships
- Corporations
- Freelancers
- Independent contractors
- Online sellers
- Service-based businesses
Eligibility requirements may differ by financial institution and business structure.
Applicants might be asked for business formation documents, tax identification details, personal identification, ownership information, or other documentation. Requirements should be confirmed directly with the institution before applying.
What Online Banking Tools Should Businesses Look For?
Useful online banking tools depend on how a company handles its financial activity.
Some businesses may prioritize mobile check deposits. Others might focus on electronic transfers, bill payments, employee account permissions, downloadable statements, or bookkeeping integrations.
Questions to ask can include:
- Can transactions be reviewed in real time or near real time?
- Are account alerts available?
- Can authorized employees receive separate access?
- Are transaction limits suitable for expected activity?
- Does the account connect with existing accounting software?
- How are checks deposited?
- How are cash deposits handled?
- What support channels are available?
- Are transfer limits disclosed clearly?
Reviewing these details before opening an account may help prevent mismatches between account capabilities and business needs.
How Can Businesses Compare Online Business Checking Accounts?
Start with normal company banking activity rather than focusing on promotional language.
Businesses may compare:
Monthly Account Costs
Check the monthly maintenance charge and any conditions tied to it. Review other transaction-related charges separately.
Transaction Activity
Estimate how many deposits, withdrawals, transfers, and payments the business typically handles each month.
Cash Handling
Companies that accept cash may need convenient cash deposit methods. Digital-first businesses may place less emphasis on this feature.
Payment Methods
Check available options for ACH transactions, wire transfers, bill payments, checks, and debit card transactions.
Digital Account Access
Review mobile and desktop functions, account alerts, statement access, permissions, and integrations.
Customer Assistance
Look at the available customer service channels and operating hours.
Frequently Asked Questions
Are online business checking accounts free?
Some accounts may have no monthly maintenance fee, while charges for other services may still apply. Review the current fee schedule for details about transfers, ATMs, cash deposits, overdrafts, and other transactions.
Can a business checking account be opened completely online?
Some financial institutions may allow eligible applicants to complete the process online. Others may require additional documentation, identity verification, or another form of review.
Do online business accounts accept cash deposits?
Some may provide cash deposit methods, though availability, locations, limits, and charges can vary. Businesses that handle cash frequently should check these terms carefully.
Is an online business checking account suitable for a small business?
It may be suitable when its fees, transaction limits, deposit methods, digital features, and account requirements align with the company’s banking activity.
What documents may be required?
Requirements depend on the business structure and institution. Possible documentation can include identification, tax information, ownership details, and business registration documents.
Finding an Account That Fits Daily Business Banking Needs
An Online Business Checking Account may provide a convenient way to handle routine company transactions through digital banking channels. The right account depends on factors such as transaction volume, cash deposits, payment methods, account fees, digital functions, and customer service needs. Before opening an account, review current account disclosures, fee schedules, eligibility requirements, and transaction limits directly from the financial institution.
Suggested Posts
All PostsAllAll PostsAll
Why Travel Rewards Benefits May Be Worth Exploring Before Your Next Vacation
- Jeff Weasley
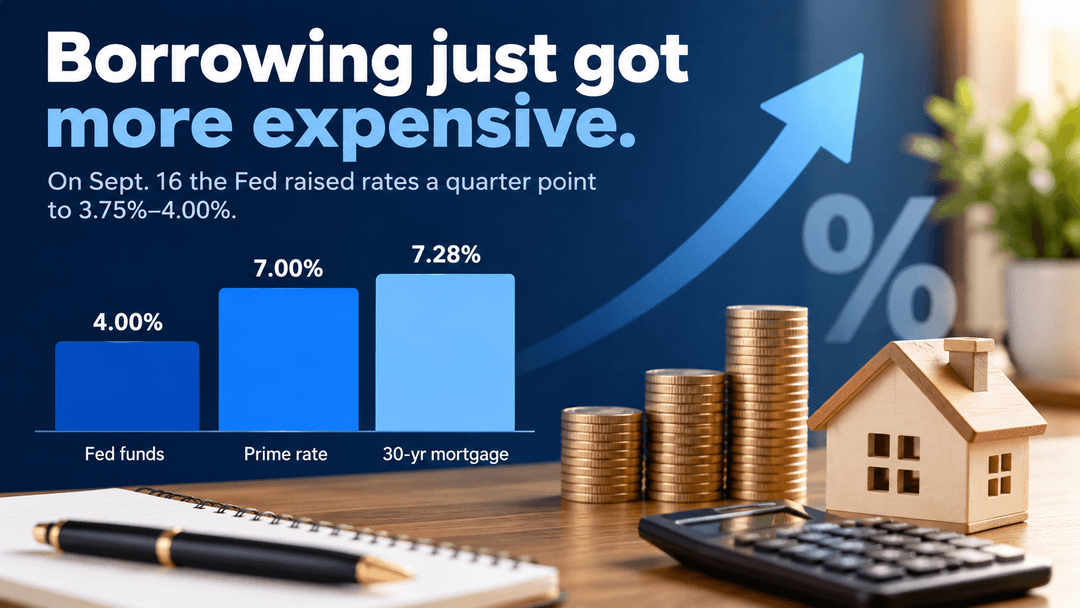
Interest Rates Explained: What They Mean for Your Money and Financial Decisions
- Katie Swift