What to Know Before Choosing an IRS Monthly Payment Plan
Owing federal taxes can put pressure on your budget, especially when paying the entire balance at once would interfere with rent, utilities, debt payments, or other regular expenses. An IRS payment plan may give eligible taxpayers additional time to pay what they owe through a short-term arrangement or monthly installments.The IRS provides several payment arrangements, and the right choice may depend on your balance, how quickly you can repay it, and the payment method you select.
Costs matter as well. Although a payment plan can spread payments over time, penalties and interest generally continue until the balance is paid.Before applying, it helps to compare the available plans, setup fees, and alternatives.
How Does an IRS Payment Plan Work?
An IRS payment plan, sometimes structured as an IRS installment agreement, allows an eligible taxpayer to pay a federal tax balance over time rather than paying the entire amount immediately.For individuals, the IRS currently provides a short-term payment plan lasting up to 180 days and long-term installment agreements involving monthly payments. Eligibility depends on factors such as the amount owed and whether required tax returns have been filed.
A payment plan does not erase the underlying tax balance. Applicable penalties and interest generally continue accumulating until the balance is fully paid.
IRS Payment Plan Options
Here is a practical comparison of common IRS tax payment options.
| Plan | Typical Use | Payment Period | Setup Fee |
|---|---|---|---|
| Pay in full | Taxpayer can cover the entire balance now | Immediate | $0 |
| Short-term plan | Individual needs additional time | Up to 180 days | $0 |
| Long-term direct debit | Monthly repayment | Based on approved arrangement | From $29 online |
| Long-term non-direct debit | Monthly repayment using other methods | Based on approved arrangement | From $69 online |
Penalties and interest generally continue on unpaid balances under both short- and long-term arrangements. Card processors may also charge separate processing fees.
Short-Term IRS Payment Plan
A short-term plan may suit an individual who cannot pay immediately but expects to clear the balance within 180 days.Individuals generally may qualify to apply online when they owe less than $100,000 in combined tax, penalties, and interest.There is currently no setup fee for a short-term plan. However, applicable penalties and interest continue until the balance reaches zero.That makes this option worth checking before choosing a longer agreement if you can realistically pay the full amount within six months.
Long-Term IRS Monthly Payment Plan
A long-term IRS monthly payment plan allows qualified taxpayers to make monthly payments when they need longer than 180 days.
Most individual taxpayers may qualify for the IRS Simple Payment Plan when they owe $50,000 or less in assessed tax, penalties, and interest and are current with applicable filing and payment requirements.
The IRS states that most taxpayers under its Simple Payment Plan may have up to 10 years to clear the balance, subject to applicable collection rules. Choosing a longer repayment period may increase the total penalties and interest paid.
How Much Does an IRS Payment Plan Cost?
IRS payment plan fees vary based on the type of agreement, application method, payment method, and whether the taxpayer qualifies for low-income treatment.
For long-term plans established online, current IRS fees include:
- $29 for a direct debit installment agreement.
- $69 for a long-term arrangement using a payment method other than automatic direct debit.
- $0 setup fee for an eligible short-term plan.
- Qualified low-income taxpayers using direct debit may have their setup fee waived.
- Low-income taxpayers who do not use direct debit may face a reduced $43 fee, which may be reimbursed when certain conditions are met.
Applying for a long-term agreement by phone, mail, or in person can cost considerably higher. Current IRS fees are $107 for direct debit and $178 for other payment methods.
Because fees can change, checking the IRS website immediately before applying is sensible.
Does Interest Stop During an IRS Payment Plan?
No. Setting up an installment agreement generally does not stop interest and applicable penalties from accumulating.This is one reason to avoid automatically choosing the smallest possible monthly payment. A lower payment may help your immediate budget, yet extending repayment can increase the total amount paid over time.Paying additional amounts when your budget permits may help reduce the outstanding balance sooner.
How to Apply for an IRS Payment Plan Online
For many eligible individuals, applying for an IRS payment plan online may be the simplest route.You will generally need an IRS Online Account. Identity verification requires photo identification. If you select direct debit, you will also need your bank routing and account numbers.
The basic process includes:
- Confirm that all required tax returns have been filed.
- Check your total balance, including assessed penalties and interest.
- Review short-term and long-term payment choices.
- Decide how much you can realistically pay.
- Select an available payment date and method.
- Submit the application through your IRS Online Account.
Eligible taxpayers applying online can receive an immediate response indicating if the payment plan request has been approved.
Can You Apply Using Form 9465?
Yes. Form 9465, Installment Agreement Request, is another way to request monthly payments.
It may be relevant when you cannot establish the desired agreement through the online system. Requests can also be made by phone in applicable situations.
The IRS generally recommends its online system when available because online applications can carry lower setup fees.
What Is a Direct Debit Installment Agreement?
A Direct Debit Installment Agreement, or DDIA, automatically withdraws the agreed monthly amount from your checking account.
Direct debit can have two practical advantages: the online setup fee is lower than the fee for a non-direct-debit agreement, and automatic withdrawals may reduce the risk of accidentally missing a scheduled payment.
The current online setup fee is $29 for direct debit compared with $69 for a non-direct-debit long-term plan.
How Should You Choose a Monthly Payment?
The lowest monthly amount should not automatically be your first choice.
Start with your regular income and necessary expenses. Then determine how much you can consistently put toward your tax debt payment plan without creating an unrealistic monthly obligation.
For example, suppose you owe $6,000 before future interest and penalties.
| Monthly Payment | Approximate Time to Pay $6,000* |
|---|---|
| $250 | 24 months |
| $500 | 12 months |
| $750 | 8 months |
| $1,000 | 6 months |
A payment amount you can maintain consistently may be preferable to an aggressive payment that puts the agreement at risk.
What Happens After the IRS Approves the Plan?
Approval creates responsibilities for the taxpayer.
You generally need to make scheduled payments on time and remain current with future federal tax obligations. Required tax returns must also remain filed.
If you become entitled to a federal tax refund while you still owe under an installment agreement, the IRS may apply the refund toward the outstanding balance. You generally must continue making your scheduled installment payments even after a refund is applied.
Can You Change an Existing IRS Payment Plan?
Certain agreements can be revised.
Depending on the agreement and your eligibility, you may be able to change your monthly payment amount, payment date, or banking details online.The IRS currently lists a $6 online revision fee for applicable changes, while changes requested by phone, mail, or in person generally carry an $89 fee. Different rules and possible reimbursements apply to qualifying low-income taxpayers.
If your financial circumstances change substantially, contact the IRS rather than simply stopping scheduled payments.
What If You Cannot Afford the Proposed Payments?
An installment agreement may not fit every financial situation.
If you cannot afford monthly payments, other IRS collection alternatives may be available depending on your circumstances. These can include temporarily delaying collection when you cannot pay or potentially applying for an Offer in Compromise if you meet the program’s requirements.
These alternatives have separate qualification standards. Taxpayers with significant balances, disputed liabilities, business tax obligations, or complicated financial circumstances may want to speak with a qualified tax professional before choosing a strategy.
Should You Hire a Tax Resolution Company?
You generally do not need to hire a private company simply to submit a standard IRS payment plan application. Eligible taxpayers can apply directly through the IRS.
Professional assistance may have greater value when your situation involves multiple unfiled returns, a large tax balance, business payroll taxes, collection activity, disputed amounts, previous defaults, or difficulty determining which IRS resolution program may apply.
Before hiring a tax resolution service, ask for a written explanation of its fees and services. Be cautious with companies that imply they can guarantee a particular settlement, eliminate tax debt, or secure an outcome before reviewing your financial circumstances.
IRS Payment Plan vs. Paying in Full
Paying in full generally costs less because it prevents future interest and penalties from continuing on an unpaid balance.
However, using emergency savings or taking expensive private debt solely to eliminate an IRS balance may create different financial concerns.
Compare the likely cost, repayment period, and impact on your monthly cash flow before deciding.How long can an IRS payment plan last?
A short-term arrangement can provide individuals up to 180 days. Long-term agreements vary. Under the current Simple Payment Plan program, most qualifying taxpayers may receive substantial time to pay, subject to IRS collection rules.
Is there a fee to set up an IRS payment plan?
Short-term plans currently have no setup fee. Long-term installment agreements generally carry a setup fee, although eligible low-income taxpayers may receive reduced or waived fees.
Can you pay an IRS payment plan early?
You can generally make additional payments toward your federal tax balance. Paying the balance sooner may reduce future interest and applicable penalties.
Can the IRS reject a payment plan request?
Yes. Eligibility requirements apply, and taxpayers generally must have filed all required returns. The IRS may request additional financial information in some cases.
Do you need a tax professional to apply?
Not necessarily. Many eligible taxpayers can apply directly through the IRS Online Payment Agreement system. Professional assistance may be useful when the tax situation is less straightforward.
Choosing a Practical IRS Payment Plan
An IRS payment plan may provide a manageable way to address federal taxes when immediate payment is unrealistic. Short-term plans can be particularly useful when you expect to pay within 180 days, since there is currently no setup fee. Long-term installment agreements can spread payments across a longer period, although interest, penalties, and setup costs need to be factored into the decision.
Before applying, compare the amount you owe, the monthly payment you can sustain, the estimated repayment period, and available IRS alternatives. Applying directly through the IRS can also help you avoid unnecessary third-party charges for a payment arrangement you may be able to establish yourself.
Suggested Posts
All PostsAllAll PostsAll
Why Travel Rewards Benefits May Be Worth Exploring Before Your Next Vacation
- Jeff Weasley
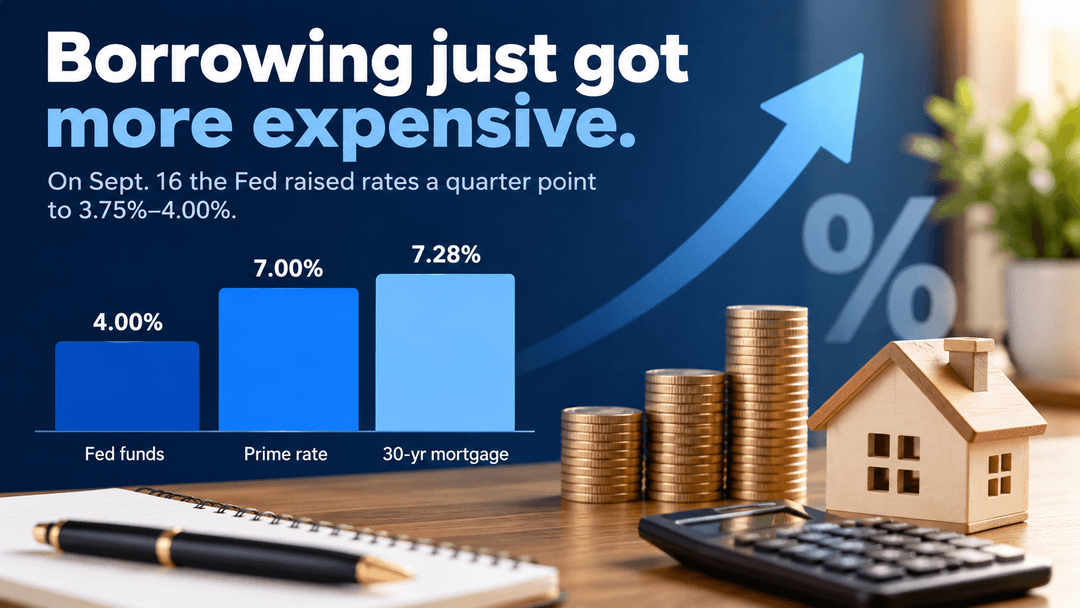
Interest Rates Explained: What They Mean for Your Money and Financial Decisions
- Katie Swift