7 Smart Ways to Avoid Paying More Interest on Credit Cards
Credit cards offer convenience and flexibility, but carrying an unpaid balance can make everyday purchases more expensive. Interest charges may accumulate quickly, especially when your card has a high annual percentage rate (APR).
Fortunately, there are practical ways to manage borrowing costs without making drastic financial changes.
Whether you’re carrying an existing balance or trying to avoid future charges, these seven strategies can help you take greater control of your credit card expenses.
1. Pay Your Statement Balance in Full
Paying your full statement balance by the due date is one of the most effective ways to avoid purchase interest.
Many credit cards offer a grace period on eligible purchases. During this period, you generally won’t owe purchase interest if you meet the card’s payment requirements.
For example, if your statement balance is $1,200, paying that amount in full by the deadline may help you avoid interest charges.
However, carrying an existing balance can affect whether your grace period applies.
Make Payments Easier
Consider setting up automatic payments for your full statement balance if you can consistently maintain sufficient funds in your checking account.
You can also schedule payment reminders to avoid missing deadlines.
2. Pay More Than the Minimum
Making only the minimum required payment can extend your repayment period and increase total interest costs.
For example, a $3,000 balance with a 24% APR could generate substantial interest charges when carried over time.
Paying more than the minimum helps reduce your outstanding balance faster.
Even an additional $25 or $50 each month may make a meaningful difference, depending on your APR, balance, and repayment schedule.
Choose an amount you can afford consistently rather than making occasional payments that strain your budget.
3. Prioritize Your Highest-Interest Balance
If you have several credit card balances, consider using the debt avalanche method.
This strategy involves making at least the minimum payments on every account while directing extra money toward the card with the highest APR.
For example, suppose you have:
- Card A: $2,000 at 27% APR
- Card B: $3,000 at 21% APR
- Card C: $1,500 at 16% APR
You would prioritize Card A before moving to Card B.
This approach generally helps minimize total interest costs when compared with paying lower-rate balances first.
4. Evaluate Balance Transfer Offers
Some credit cards provide introductory APR promotions for eligible balance transfers.
These offers may temporarily reduce interest charges on transferred debt, giving you an opportunity to repay the balance more efficiently.
However, promotional offers come with conditions.
Before applying, review:
- Balance transfer fees
- Promotional APR duration
- APR after the promotion expires
- Eligibility and transfer restrictions
- Interest treatment for new purchases
A balance transfer fee can reduce potential savings, and an unpaid balance may become subject to a higher rate after the introductory period.
Calculate your expected repayment costs before deciding whether transferring debt makes financial sense.
5. Ask About a Lower Interest Rate
You may be able to request a lower APR from your existing credit card issuer.
Approval isn’t guaranteed, but contacting customer service may be worthwhile if you have a positive payment history.
Before calling, review your current APR and account terms.
Explain that you’re evaluating your borrowing costs and ask whether a lower rate is available.
If you’re experiencing financial difficulties, you can also inquire about hardship assistance or alternative repayment arrangements.
Any available rate reduction could help lower future interest expenses on an outstanding balance.
6. Avoid Expensive Cash Advances
Cash advances often have different terms from ordinary credit card purchases.
They may carry higher APRs, transaction fees, and interest that begins accumulating immediately.
Unlike eligible purchases, cash advances generally don’t receive a grace period.
This means borrowing cash through your credit card can become expensive even when you repay the amount relatively quickly.
Before using this feature, review the applicable fees and interest charges.
If you need emergency funds, compare the total costs of available alternatives rather than relying automatically on a cash advance.
7. Create a Consistent Repayment Plan
A structured repayment plan can help you manage outstanding balances and avoid unnecessary interest.
Start by listing your credit card balances, APRs, minimum payments, and due dates.
Then determine how much extra money you can reasonably allocate toward repayment each month.
Consider reducing discretionary expenses temporarily and directing those savings toward your priority balance.
Review your progress regularly and adjust your plan when your income or expenses change.
Consistency is more valuable than setting an unrealistic repayment target.
Build Better Credit Card Habits
Avoiding unnecessary interest starts with understanding your credit card terms and making payments that support your budget.
Paying statement balances in full when possible, reducing high-interest debt, and evaluating promotional offers carefully can help limit borrowing costs.
You don’t need to change every financial habit immediately.
Start with one manageable improvement, such as increasing your monthly payment or reviewing your highest-interest account.
Over time, these decisions can help you reduce debt and maintain greater control over your finances.
Suggested Posts
All PostsAllAll PostsAll
Why Travel Rewards Benefits May Be Worth Exploring Before Your Next Vacation
- Jeff Weasley
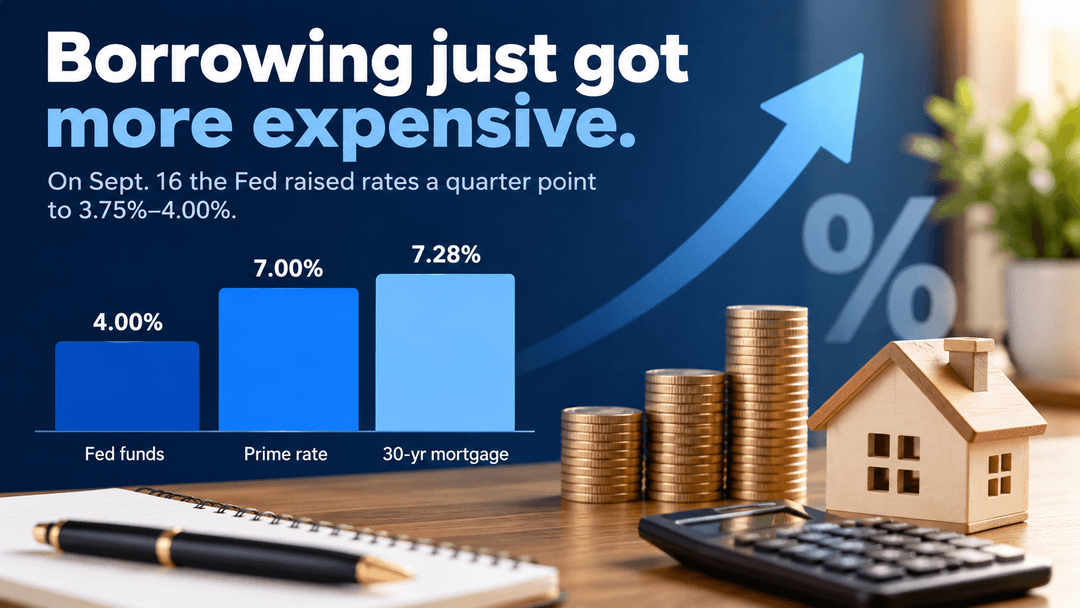
Interest Rates Explained: What They Mean for Your Money and Financial Decisions
- Katie Swift